Prime Brokerage, Rehypothecation, and Counterparty Risk
How collateral reuse links a broker, a hedge fund, and cash lenders—and why the U.S. customer-protection rule’s 140% definition is not a universal reuse cap or recovery guarantee.
Publication & corrections: infostoa · Editorial standards
Individual author and specialist reviewer information is not provided for this article.
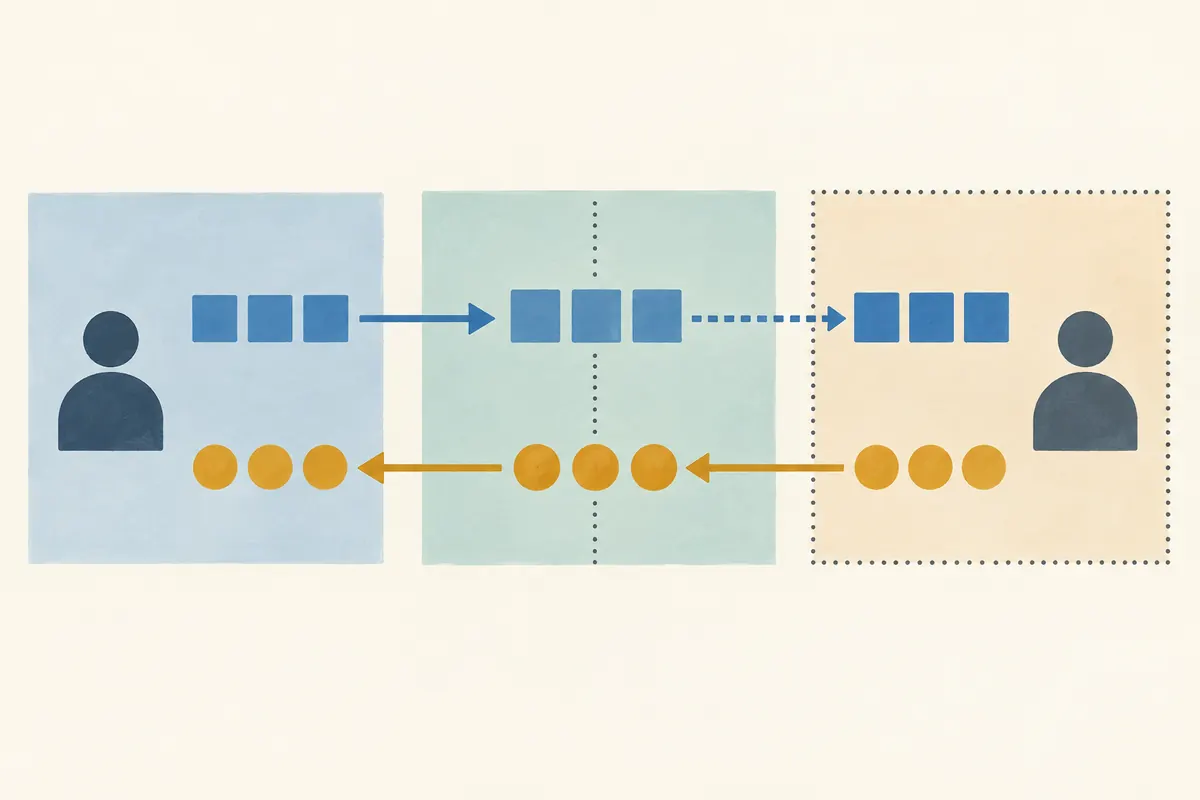
Prime brokerage bundles securities lending, settlement, custody, and financing for hedge funds. Rehypothecation is a structure in which a client asset may support the broker’s other financing when the agreement and applicable rules allow it. This connects funding markets, but it does not give a collateral provider and a cash lender the same claim or recovery path. The 140% figure in a U.S. rule is not a universal ceiling on all reuse.
How collateral can fund another transaction
A hedge fund may borrow from a prime broker against securities. Federal Reserve economist Sebastian Infante’s study models a dealer intermediating repo funds and collateral between cash lenders and prime-brokerage clients. Different haircuts on the two sides can create initial liquidity for the dealer. This is one modeled financing channel, not evidence that every customer asset follows the same route.
Actual rights depend on the account agreement, asset, legal form of the transaction, institutional status, and jurisdiction. The word rehypothecation alone does not prove that ownership has wholly transferred or that the customer can immediately recover the same security. The documents should be checked for reuse permission, substitute-collateral terms, return timing, and whether the transaction is a repo or securities loan.
What the 140% definition means
The eCFR text of the SEC customer-protection rule defines excess margin securities as customer margin securities whose market value exceeds 140% of total debit balances in the relevant margin accounts and which the broker identifies as not constituting margin securities. The rule also requires a broker-dealer promptly to obtain and maintain physical possession or control of fully paid and excess margin customer securities. Thus, 140% is part of a definition used to identify excess margin securities; it is not blanket permission to reuse that fraction of every customer’s collateral.
The rule contains account- and transaction-specific provisions. A narrow OTC derivatives dealer exception requires written notice that collateral may be repledged or used, that the counterparty may likely be an unsecured creditor if the dealer fails, and that SIPA may not protect it. That exception should not be generalized to all prime-brokerage accounts. The eCFR says its current online text is authoritative but unofficial and is not the official legal edition. Application requires the current rule and account agreement together.
Why dealer stress can affect the sides differently
Infante’s 2015 Federal Reserve staff paper is preliminary and says its analysis and conclusions are the author’s, not necessarily the Board’s. In the model, a hedge fund provides collateral to a dealer, which uses it in a repo with a cash lender. The study explains why collateral providers and cash lenders could reassess a relationship differently when the dealer’s solvency is questioned. Its empirical discussion is confined to the U.S. bilateral and tri-party repo data it examined.
The paper does not establish that collateral providers always lose more or that every market experiences the same run. Results depend on assumptions about collateral value, dealer default, correlation with collateral outcomes, and counterparties’ rights. The expert interpretation is to distinguish the dealer’s liquidity benefit from the customer’s collateral-return exposure. If one asset supports multiple contracts, settlement delays, missing substitute collateral, and claim priority may matter; a particular outcome still depends on documents and insolvency proceedings.
Questions to ask in the account documents
Check whether the agreement permits reuse of customer assets, which assets and transactions it covers, whether the client can choose restrictions, and whether collateral can move to another institution. Then locate terms for margin shortfalls, close-out, collateral return, notices, and substitution. Compare terms such as fully paid and excess margin with the rule’s definitions and the account’s classification rather than everyday usage.
These questions are a reading framework, not a legal conclusion or an assessment of a particular broker’s safety. Rule 15c3-3 describes custody and control obligations for U.S. broker-dealers; the Federal Reserve paper presents an economic model based on particular repo-market evidence. Actual treatment of an asset or insolvency claim depends on the agreement, institutional status, jurisdiction, and current law. This overview cannot guarantee collateral availability or return timing.