Municipal Bond Insurance: The Monoline Promise and Credit Risk
How a municipal bond wrap adds a contractual payment promise, why guarantor credit matters, and which current disclosures to compare.
Publication & corrections: infostoa · Editorial standards
Individual author and specialist reviewer information is not provided for this article.
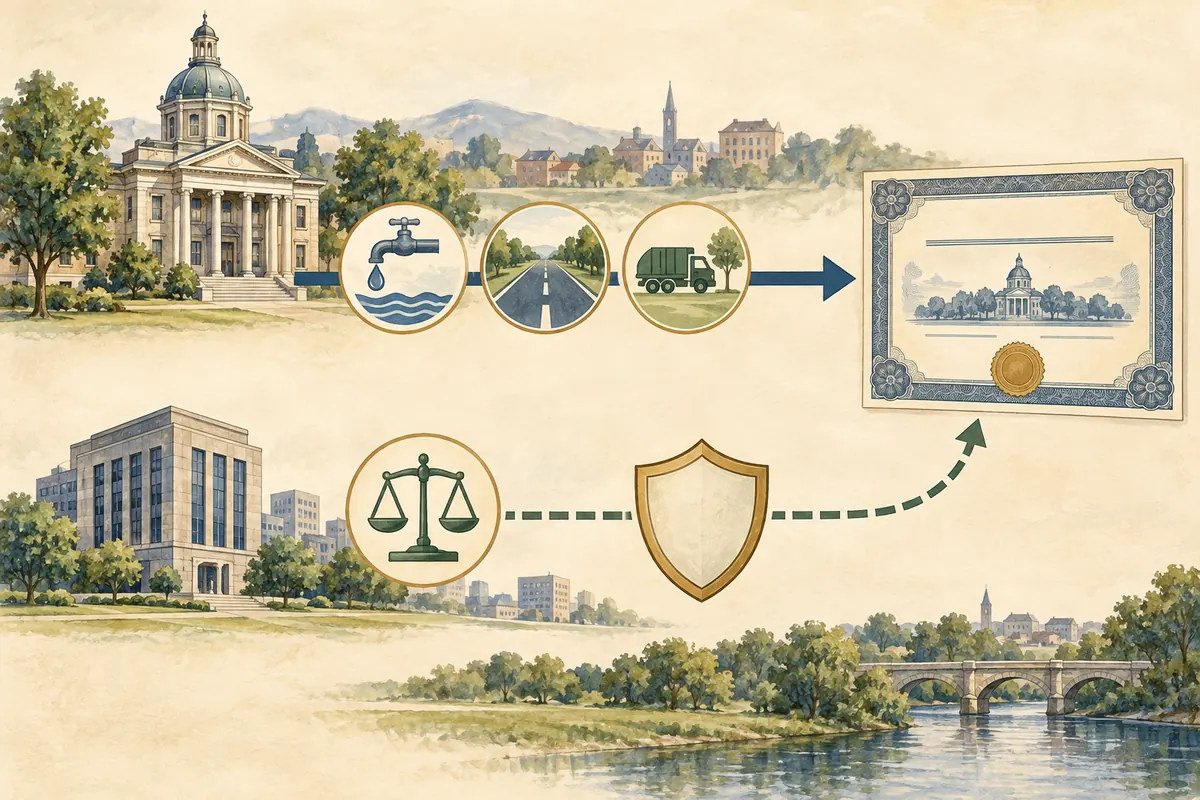
Insurance adds a separate contractual promise
A municipal bond monoline wrap is a form of credit enhancement: under the insurance contract, a guarantor supplements payment when the municipal issuer does not make promised principal or interest payments. In testimony to Congress on May 20, 2009, Federal Reserve staff official David W. Wilcox described financial guarantors charging a fee in exchange for promising timely payment on insured bonds if a municipality could not pay. The guarantee does not change the municipality’s finances; it adds the guarantor’s contractual promise for the covered obligations.
A label such as “insured” or a high rating is not enough to understand that promise. Read the offering documents to identify who owes what, which payment events trigger coverage, how claims must be made, and how principal and interest are treated. The issuer’s fiscal condition and the revenues supporting a project remain relevant even when insurance is present.
A higher rating does not remove risk
A joint investor notice from the Municipal Securities Rulemaking Board (MSRB) and FINRA says insurance may raise a bond’s overall credit rating, but protection operates only to the extent promised by the insurer. If the guarantor’s financial strength weakens, the perceived value of its promise can also weaken. Do not assume that the rating shown when a bond was issued remains current; check current information about the issuer and guarantor separately.
Insurance does not guarantee a bond’s market price, liquidity, or interest-rate performance. A high rating also does not mean an investor can sell at a desired time. Read the insurance alongside taxes, the repayment source, maturity, and call provisions, and do not infer safety or suitability from the existence of a wrap alone.
Expert perspective: separate the insured rating from guarantor credit
MSRB and FINRA warn that a high overall rating reflecting insurance may not describe the issuer’s own financial condition. If issuer and guarantor ratings differ, check which rating and date are displayed, then compare current issuer disclosures with current information on the insurer. The notice dates from 2009; it does not report present-day ratings.
The 2007–09 crisis illustrates guarantor exposure
Wilcox’s 2009 testimony describes how losses on nonmunicipal credit exposures weakened some guarantors’ capacity to write new policies and reduced the perceived value of policies already issued. It traces pressures in parts of the variable-rate municipal market to concerns about guarantor strength that emerged in late 2007. The episode illustrates that issuer credit and guarantor credit are distinct, yet the guarantor’s condition can affect how an insured bond is viewed in the market.
This is historical testimony, not a current market snapshot. Its insurance shares, rates, and conditions should not be repeated as present-day figures, and the episode does not predict the outcome for every monoline guarantee or today’s municipal bonds. Assess a current issue using its current official statement, continuing disclosures, insurance contract, and up-to-date information about the guarantor.
A document checklist for an insured issue
Locate the bond’s official statement and the latest material-event disclosures, including through EMMA, and compare them with the actual insurance agreement. Record the insurer, covered payments, exclusions, claim conditions, and any trustee or insurer role. MSRB and FINRA’s notice emphasizes that ratings and issuer information can change after issuance, so note the date of the displayed rating and compare it with current information.
A concise review note can separate (1) the issuer and repayment source, (2) insured payments and exceptions, (3) claims procedures and the roles of the trustee or guarantor, (4) the date of current credit information for both issuer and insurer, and (5) risks the policy does not cover, such as price, liquidity, or call risk. This is an educational document-reading sequence, not a recommendation to buy or sell a specific bond or a promise of returns. The 2009 sources are used for historical structure and crisis context only.
Sources
- David W. Wilcox, “Municipal finance” — May 20, 2009 congressional testimony by a Federal Reserve Board deputy director; historical account of bond insurance and market stresses.
- MSRB and FINRA, “MSRB and FINRA Issue Joint Investor Education Notice” — June 30, 2009 investor notice on guarantor strength, issuer disclosures, and rating limits.