Commercial Paper Ratings and Liquidity Backstops Address Different Risks
Understand CP maturity and rollover risk, what ratings do not guarantee, and how bank liquidity lines differ from credit enhancement.
Publication & corrections: infostoa · Editorial standards
Individual author and specialist reviewer information is not provided for this article.
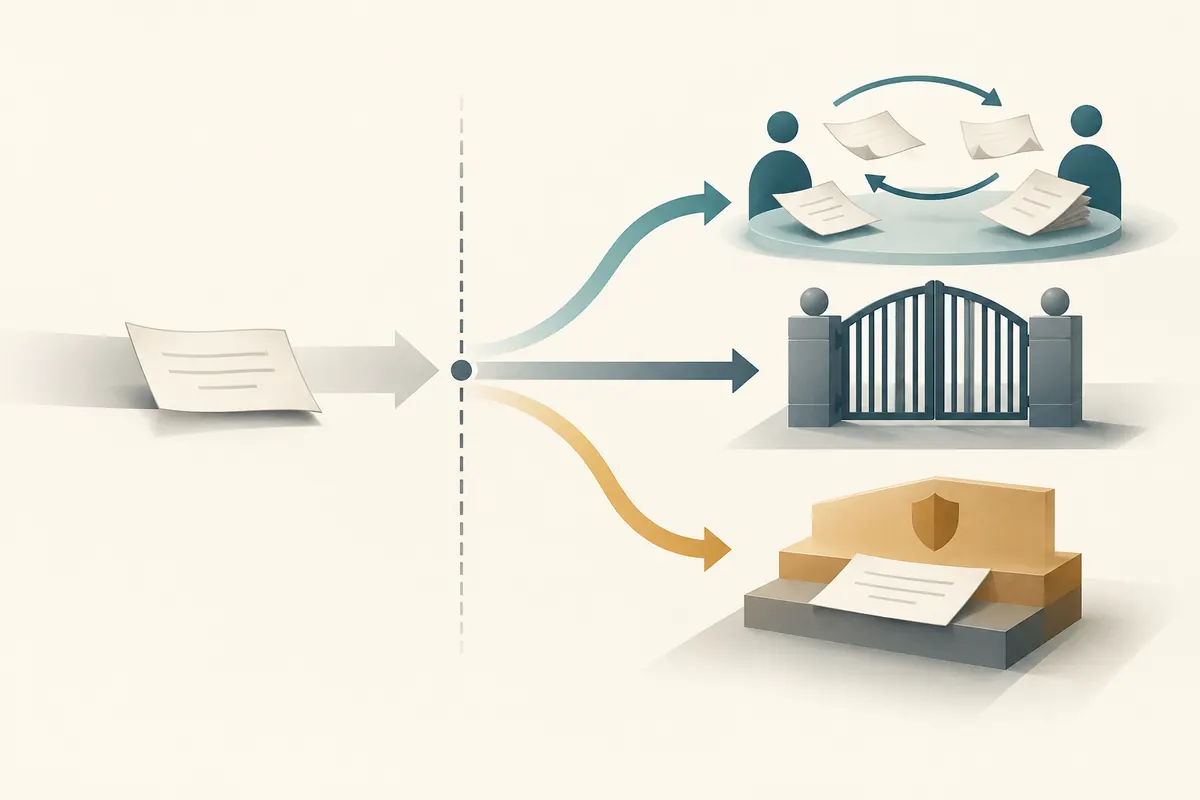
Commercial paper (CP) is a short-term promissory security companies use to raise cash. Its short maturity and flexibility can fit near-term operating needs, but each maturity creates a need to issue new paper or repay from another source. Credit ratings, a bank credit line, and market-wide liquidity facilities address different risks; they should not be bundled into one generic “safety net.” Federal Reserve data explain U.S. CP statistics and rating tiers, while a 2024 Federal Reserve research note examines how short-term financing choices create rollover exposure.
How commercial paper creates short-term funding
Companies commonly issue CP to cover near-term cash needs such as payroll, inventory, or other current transactions. The Federal Reserve’s U.S. CP materials describe maturities of up to 270 days and an average maturity of about 30 days. Those figures describe the scope of that U.S. data source; they are not fixed terms for every CP program worldwide. Contract terms and regulation must be checked for the issuer and jurisdiction in question.
Short-term funding can be less costly than long-term debt and may offer flexibility, but a short maturity brings principal repayment forward. At each maturity, the issuer must find new buyers or use cash, a bank loan, or another source to repay the paper. Even when a market is functioning, changes in credit quality or interest rates can raise the cost of rolling over debt. During market stress, issuance may become difficult or unavailable.
A credit rating is an assessment, not a promise of cash
A credit rating assesses the risk that an issuer or program will meet its debt obligations. The Federal Reserve’s CP statistics use short-term ratings from nationally recognized rating organizations to define data tiers. Those tiers are statistical categories, not statements that a highly rated note is risk-free or principal-protected. Rating symbols and inclusion criteria differ across agencies, data sources, jurisdictions, and dates. A historical Tier 1 or Tier 2 definition should not be treated as a universal rule for every current market.
A rating provides information about credit risk, but it does not establish that an issuer will have enough cash on a particular maturity date or that investors will buy new paper. Credit and liquidity risks interact without being identical. A company may remain creditworthy while risk-averse investors reduce purchases or market conditions make refinancing difficult.
Treat support as contract-specific
A claim that a bank line or credit enhancement exists does not guarantee repayment of CP. The actual rights and coverage must be checked in the governing agreement and applicable law. The covered issue and beneficiary, availability conditions, amount, currency, and maturity can vary by contract. Without the agreement, do not infer when a facility supplies cash or whose losses it covers. The Federal Reserve’s statistical definitions describe U.S. CP scope and categories; they do not establish what an issuer’s bank facility promises.
Expert perspective: rollover risk links the issuer to market conditions
A 2024 Federal Reserve FEDS Note describes CP as financing for near-term business needs and explains that short maturities create rollover risk. It also notes that prime money market funds are important investors, so investor demand can change with risk appetite. Its sample and empirical results should not be generalized to every issuer or period. The useful point is that funding cost alone is incomplete: the maturity schedule, investor base, alternative funding access, and market conditions can move together.
Review issuance and repayment together
When explaining or comparing a CP structure, record the issuer, maturity profile, investor base, rating date and methodology, available cash and committed facilities, and draw conditions separately. A rating or market rate observed today cannot settle whether refinancing will be available later. Federal Reserve rate and outstanding statistics are aggregate measures of market segments; they are not a forecast of a particular issuer’s financing cost or ability to repay.
An issuer can compare upcoming maturities with cash and committed facilities under different stress assumptions and examine whether funding sources or due dates are concentrated. An investor needs to consider the security’s credit risk, contractual enhancement, market liquidity, and personal risk tolerance separately. This article explains general structures; it is not a rating of a specific CP security or investment advice.