CLO Equity Tranches: Waterfalls, Subordination, and Risk
Understand how a CLO pays its tranches, why coverage tests can stop equity distributions, and how reinvestment and manager decisions affect residual cash.
Publication & corrections: infostoa · Editorial standards
Individual author and specialist reviewer information is not provided for this article.
A CLO equity tranche is not an ordinary bond with a promised coupon. It is the most junior interest in cash left after expenses and higher-ranking debt are paid under the deal documents. Credit losses or a failed coverage test can reduce or divert that cash, while equity may absorb losses before senior tranches. A projected yield alone cannot establish how safe or suitable an investment is.
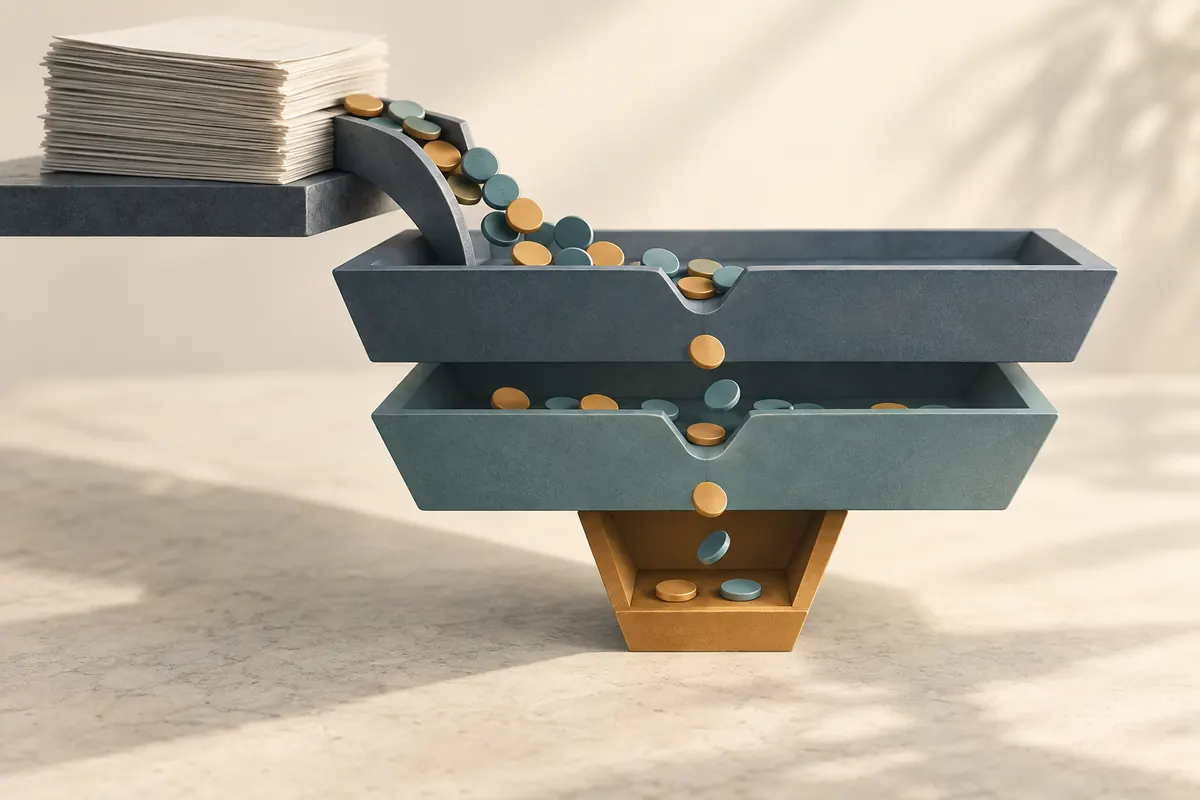
How a CLO turns loans into ranked claims
A collateralized loan obligation (CLO) pools corporate loans and issues debt tranches and an equity interest with different payment priorities and loss exposure. When borrowers pay interest or principal, the transaction's cash-flow waterfall allocates money according to its legal documents. Expenses and debt claims generally come ahead of residual equity, although the exact order, tests, and exceptions vary by deal. A prospectus filed with the U.S. Securities and Exchange Commission by Flat Rock describes residual equity cash and possible cash diversion after coverage-test failures. It is issuer disclosure about contemplated investments, not SEC-authored advice or a determination of another CLO's payments. SEC-filed prospectus
Equity receives residual cash and sits behind the debt
Unlike a senior note with contractual interest and principal terms, an equity tranche generally receives what remains after higher-ranking claims and permitted expenses are paid and deal tests are satisfied. Defaults, recoveries, prepayments, borrowing costs, and timing all change the residual. Junior priority can give equity access to residual cash in favorable conditions, but it also leaves that interest exposed when losses accumulate. The protective cushion for senior debt can be used up before equity has any remaining value. Subordination organizes who bears losses; it does not eliminate them or guarantee a distribution.
Why an overcollateralization test can redirect cash
An overcollateralization (OC) test compares collateral and outstanding debt under a formula defined in the transaction documents. If the test fails, the waterfall may redirect cash that otherwise could have reached equity toward repayment of more senior debt. This mechanism is intended to protect higher-ranking claims, and it explains why equity cash flow can be interrupted even when the underlying loans still produce some payments. The test's numerator, exclusions, thresholds, cure mechanics, and priority are deal-specific. Do not apply one threshold or a simplified diagram to every CLO. Flat Rock's filed prospectus illustrates possible cash diversion after a coverage-test failure; it is issuer disclosure, not an SEC endorsement. Flat Rock prospectus filed with the SEC
S&P Global Ratings specialist analysis: cash-flow and market-value structures
A cash-flow CLO is generally analyzed through loan interest and principal collections, defaults, recoveries, and contractual coverage tests. S&P Global Ratings’ archived structural comparison says cash-flow CLO performance is primarily linked to collateral defaults, recoveries, and excess cash flow, whereas market-value CLOs depend more directly on collateral prices and the manager’s ability to maintain asset value; market-value structures typically permit more trading flexibility. Because that analysis is from the 2008 era, it supports the structural distinction only, not current market statistics or present deal terms. S&P Global Ratings structural comparison These labels describe a structural distinction; the governing documents still determine a particular deal's rules and the manager's trading authority. Falling loan prices can create valuation pressure, while borrower defaults can weaken collections and coverage. Active management does not remove either form of risk. A manager's decisions and the deal's reinvestment terms matter alongside the type label.
Reinvestment brings new loans and new uncertainty
During a reinvestment period, a manager may use principal proceeds to buy eligible assets again. The documents specify what may be purchased or sold and any limits on quality, concentration, maturity, or ratings. Market rates, loan prices, and borrower credit can differ from conditions when the original portfolio was assembled, so reinvested proceeds can change the future mix of risk and cash flow. The SEC-filed prospectus lists defaults, recoveries, prepayments, reinvestment terms, financing costs, market prices, and waterfall structure among modeling variables. Past performance cannot fix future distributions; projections depend on assumptions.
What to inspect in the transaction documents
Before evaluating an equity interest, read the payment priority, OC and interest-coverage tests, cash-diversion triggers, eligible assets, reinvestment end date, fees, liquidity limits, and early-redemption provisions. Treat a projected distribution as a scenario, not a promise, and examine how it changes when default, recovery, interest-rate, and reinvestment assumptions move. This article explains a structure; it does not decide whether a particular CLO suits an investor. Equity can lose all of its value, deal terms differ, and these interests can be difficult to sell. If those risks exceed your ability to evaluate, seek independent advice; a headline yield cannot replace document review.