CD Laddering: Maturity Spacing, Liquidity, and the Risks That Remain
Staggered maturities can spread reinvestment dates, but do not remove liquidity, rate, or insurance risks. Compare bank and brokered CDs by their actual terms.
Publication & corrections: infostoa · Editorial standards
Individual author and specialist reviewer information is not provided for this article.
A certificate-of-deposit ladder divides money among CDs with different maturity dates. As each portion matures, you can spend it or reinvest at the rates then available. The schedule can spread reinvestment dates, but it does not guarantee a return or remove the risks of early access, inflation, issuer terms, or deposit-insurance limits. Build the ladder around when the cash is needed, then compare the actual contract and account structure for each rung.
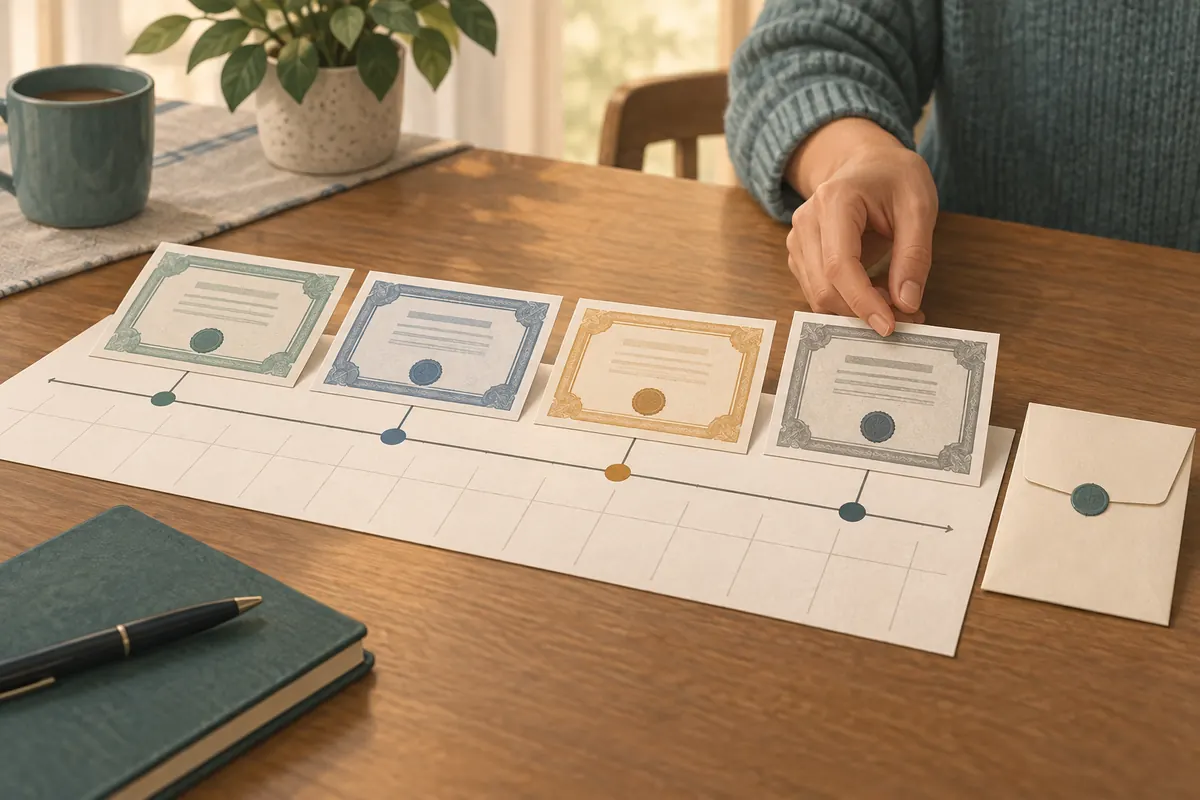
Start with the dates when you need cash
Set aside emergency reserves and near-term expenses before committing money to fixed terms. Only the portion that can remain invested until maturity belongs in the ladder. Splitting an amount among, for example, three-, six-, nine-, and twelve-month maturities creates staggered dates after the first setup. Those intervals are an illustration, not a recommended allocation; minimum deposits, product terms, taxes, and your cash-flow needs determine what is workable.
For every maturity, write down whether principal and interest will be withdrawn, held in a liquid account, or reinvested. Check automatic-renewal rules and the deadline for changing an instruction. A ladder is primarily a calendar and cash-flow arrangement. If rates rise, a maturing rung may be reinvested at a higher rate, while existing fixed-rate CDs generally keep their contracted rate. If rates fall, the next rung may earn less. Staggering maturities spreads those decisions through time; it does not predict which direction rates will move.
Understand what maturity spacing can and cannot do
A longer fixed term can preserve a contracted rate for longer, while shorter terms return cash sooner for another decision. That creates a trade-off between rate certainty and flexibility. If all funds mature together, you face one large reinvestment decision at one market rate. If maturities are staggered, only part of the balance is repriced at a time, but the portfolio may still earn less after rates fall or lag a fast rise.
A bank-issued CD may impose an early-withdrawal penalty or reduce interest if you cash it in before maturity. Do not treat the nearest rung as a substitute for immediately available emergency cash. Compare annual percentage yield, when interest is paid, renewal instructions, and the exact early-withdrawal clause. The same headline rate can produce different cash flows when compounding, payout timing, or penalties differ.
Treat bank CDs and brokered CDs differently
A CD bought directly from a bank and a brokered CD held through an investment account may have different exit routes. The SEC’s investor bulletin explains that brokered CDs can often be sold in a secondary market, but a market may not exist for a particular CD at the time you need cash. If rates have risen since purchase, buyers may value the older, lower-yielding CD at a discount, so a sale can return less than the original principal. Sales fees can add to that loss.
Brokered CDs may also be callable: the issuing bank can redeem the CD early under its terms, while the holder does not receive an equivalent right to demand redemption. Before treating one as a ladder rung, identify the issuing bank, exact maturity and call terms, potential sale fees, and how your ownership is recorded. “No early-withdrawal penalty” does not mean a brokered CD is guaranteed to be liquid or to preserve principal if sold early. Direct-bank CDs also vary, so the written contract controls.
Check deposit insurance and total exposure
The FDIC lists CDs among deposit products that may be insured at an FDIC-insured institution. Coverage depends on both the product and how ownership is categorized; it is not simply a separate limit for every account number. Aggregate deposits you already hold at the issuing bank with the proposed rung and confirm the relevant ownership category. For brokered CDs, verify the issuing bank and the recordkeeping or custodial arrangement rather than assuming a brokerage statement alone resolves coverage.
A practical ladder worksheet can include principal, APY, maturity date, interest-payment schedule, renewal instruction, issuing bank, ownership category, and the cost or price risk of early access. Revisit the worksheet when a rung matures or your cash needs change. Taxes and inflation also affect what the interest can buy, so a nominal rate is not a guaranteed gain in purchasing power. Avoid projecting the current rate across every future reinvestment date.
Expert perspective: a ladder is a schedule, not a single safe product
Read together, FDIC deposit-insurance rules and the SEC’s brokered-CD bulletin show why the word “ladder” cannot substitute for examining each holding. A practitioner distinguishes an insured bank deposit from a security-positioned brokered CD, checks the issuer and ownership records, and asks what an early sale would cost under current market conditions. For a known expense, matching maturity dates and keeping separate liquid reserves may matter more than reaching for the highest advertised yield. For an investment objective, reinvestment, inflation, callability, and liquidity risk still need separate consideration.